What a wind mitigation inspection is
A wind mitigation inspection is a standardized assessment of the features that help a house resist hurricane and high-wind damage. In Florida it is reported on the OIR-B1-1802 form, which insurers use to apply mandatory wind mitigation credits.
It is not the same as a four-point inspection. A four-point looks at the overall condition of the roof, electrical, plumbing and HVAC for underwriting purposes. A wind mitigation inspection is specifically about wind resistance and is used for discounts.
Most reports are valid for five years, or until the roof is replaced or the documented features change.
What the inspection documents
- Roof covering: material, age and whether it meets the current code.
- Roof shape: hip, gable, flat or complex — hip roofs generally receive better credits.
- Deck attachment: nail size, spacing and type used to attach the sheathing.
- Roof-to-wall connection: straps, clips, anchors or toe-nails, and how they are secured.
- Secondary water resistance: a sealed or taped underlayment that limits water intrusion if the roof covering fails.
- Opening protection: impact-rated windows, doors and garage doors, or documented shutters.
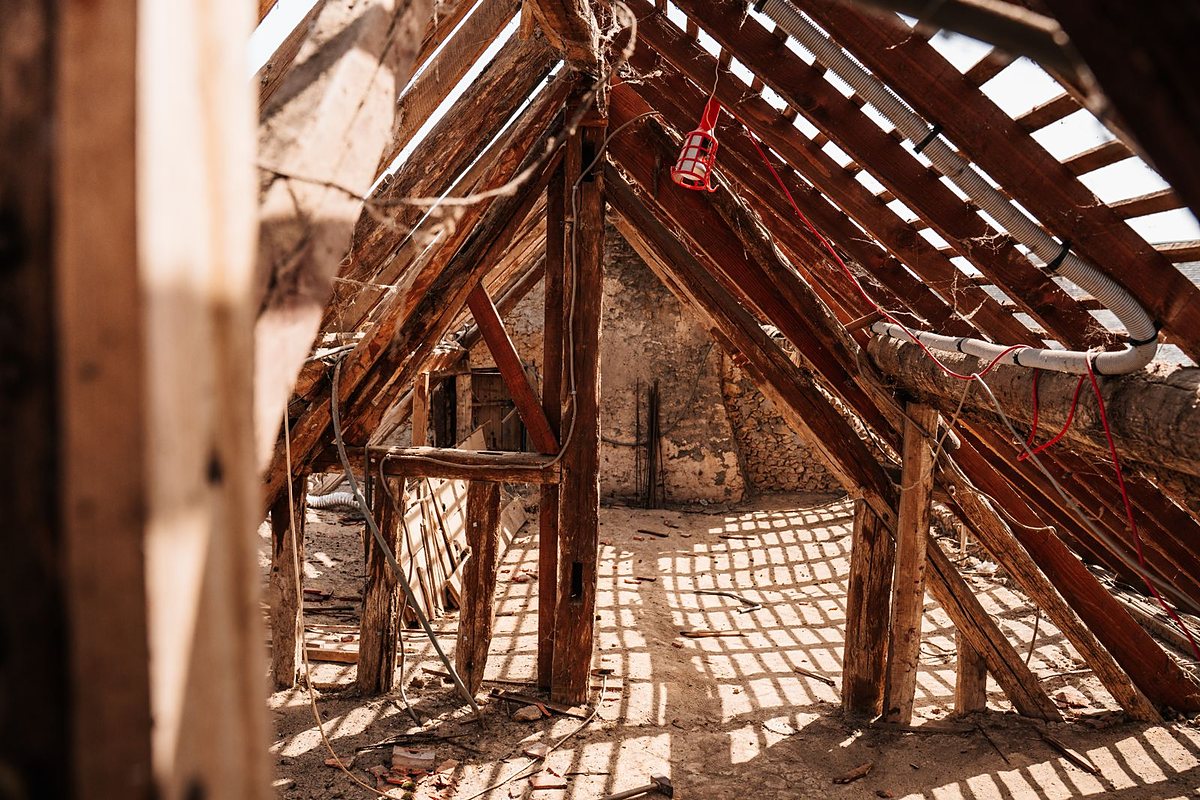
Some features can only be verified in the attic, and some require removing a small amount of insulation or looking under the roof covering. The inspector documents what is visible and notes what could not be verified.
Not sure if your home qualifies for wind credits?Call and describe what you are seeing — we will give you a straight answer before anyone climbs up.
Call (352) 614-6215How much can it save?
Florida law requires insurers to offer wind mitigation discounts, but the amount varies by carrier, home and feature set. Homes with a hip roof, a secondary water barrier, strong roof-to-wall straps and impact protection see the largest credits. Savings commonly run from a few hundred dollars a year to well over a thousand on higher-value homes.
The inspection usually pays for itself in the first renewal. Even if the report confirms the home already has the best features, it gives you documentation for future renewals and a baseline if you re-roof.
If your home does not qualify for the strongest credits, the report tells you which improvements would move the needle — useful before a roof replacement.
When to schedule one
- You are buying a home and want to confirm the wind features before closing.
- Your premium increased and you have not had an inspection in five years.
- You just replaced the roof and want the new features documented.
- You added impact windows, a garage door or shutters.
- Your insurer is asking for updated documentation.
- You are comparing policies and want accurate credits applied.
The best time is immediately after a roof replacement, while the underlayment, deck attachment and roof-to-wall connections are accessible and documented.
My Safe Florida Home and other programs
Florida's My Safe Florida Home program has offered state-funded wind inspections and matching grants for eligible homeowners to harden their homes, including roof and opening upgrades. Funding and eligibility change, and the program has had waiting lists, so check the current status before assuming you qualify.
Whether or not a grant is available, the inspection itself is inexpensive and the documentation is useful. We can coordinate the roof portion of any recommended work and provide documentation for the program.
Program rules and funding are set by the State of Florida and can change; confirm details with the program directly.
Ready to get a real answer?Call (352) 614-6215 and describe what your roof is doing. Written estimates across Gainesville and Alachua County.
Call (352) 614-6215Questions & answers
Frequently asked questions
Straight answers about wind mitigation inspection in Gainesville.
How much does a wind mitigation inspection cost in Gainesville?
Typically $100–$200. The report usually pays for itself at the first renewal through wind mitigation credits. We will confirm the fee before booking.
How long is a wind mitigation report valid?
Generally five years, or until the roof is replaced or the documented features change. Some insurers request a newer report, so check with your agent.
What is the difference between a wind mitigation and a four-point inspection?
A wind mitigation inspection documents wind-resistant features for discounts. A four-point inspection assesses the condition of the roof, electrical, plumbing and HVAC for underwriting eligibility. Insurers may request either or both.
Will the inspection definitely lower my premium?
Not always. The credit depends on your home's features and your carrier's rating plan. The report documents what exists; if the home already has the best features, the value is confirmation and documentation rather than new savings.
Can you do the inspection if you are also replacing my roof?
Yes, and it is the best time. New underlayment, deck attachment and roof-to-wall connections can be documented during installation, which produces the strongest report.
Do you perform the inspection yourselves?
We coordinate inspections with appropriately licensed Florida inspectors and provide the roof documentation. That keeps the report valid for insurers and independent of the sales process.
Roofer near Gainesville works across Alachua County and North Central Florida.